Autopay prevents missed bills, but households still need a review habit so price hikes, subscriptions, insurance changes, and card renewals do not slip through unnoticed.
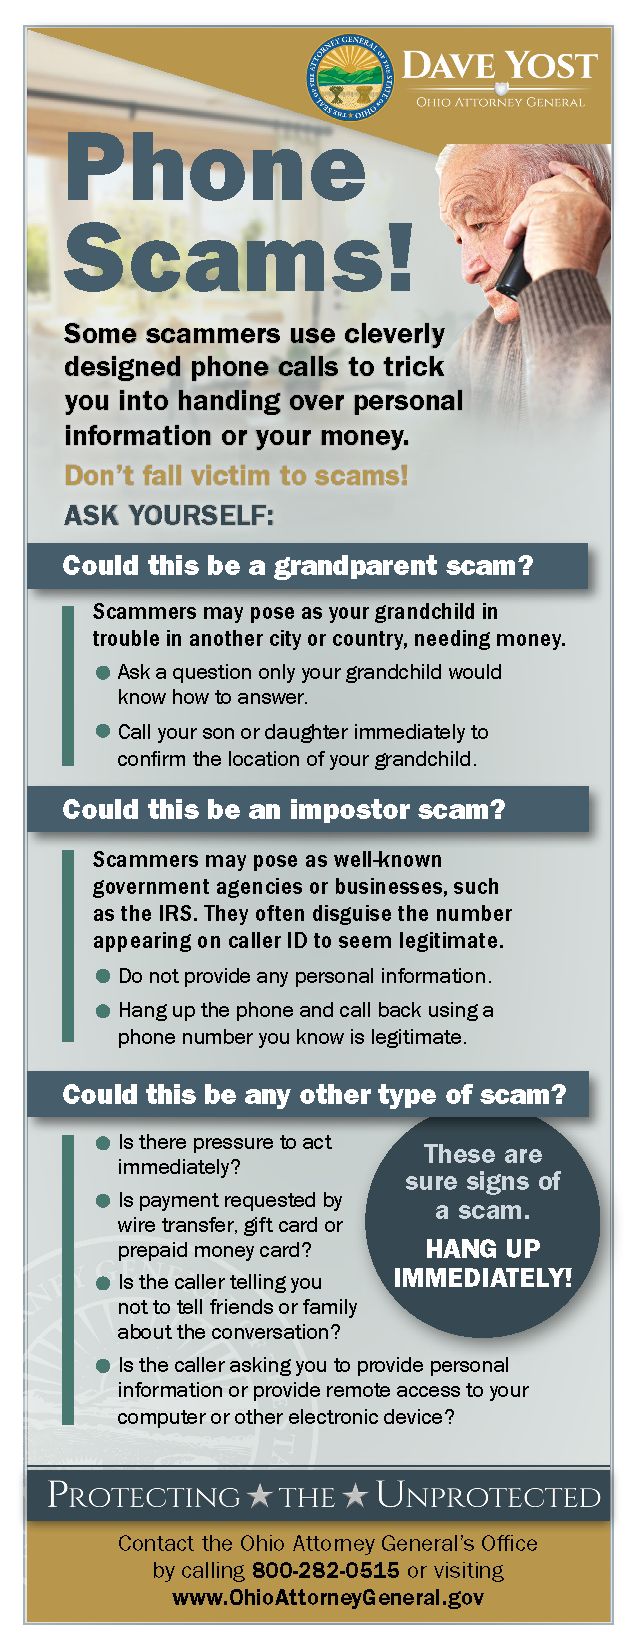
Old workplace retirement accounts are easy to ignore, but fees, investment drift, beneficiary records, and login access can all affect a household's retirement plan.
A collection letter can feel urgent, but consumers should verify the debt, know their rights, and protect the household budget before sending money.
Marketplace premium tax credits are based on estimated income, so job changes, raises, side income, or retirement shifts can affect what households owe later.
A store card discount can look harmless at checkout, but high APRs, deferred interest, and narrow rewards can make the deal weaker than it sounds.
A payable-on-death beneficiary form can decide where cash goes later, so households should review account titles and beneficiaries alongside rates and insurance.
Before rolling an old 401(k), compare fees, investment options, creditor protections, tax treatment, and whether the move creates avoidable mistakes.
IRMAA can raise Medicare Part B and Part D premiums when income crosses certain thresholds, so retirees should watch more than their tax bracket.
A CD ladder can spread maturity dates so savers do not have to bet the whole cash reserve on one interest rate or one bank deadline.
A credit freeze can block many new-account fraud attempts, but it does not replace account alerts, password cleanup, or watching existing cards and bank accounts.
Author’s pick


news via inbox
Subscribe to our newsletter to get latest news & updates.