Higher deductibles can lower premiums, but households should make sure they could actually pay the deductible after a home, auto, or health claim.
Minimum payments can protect against late fees, but households should know how interest, new purchases, and payoff timelines can keep balances alive.
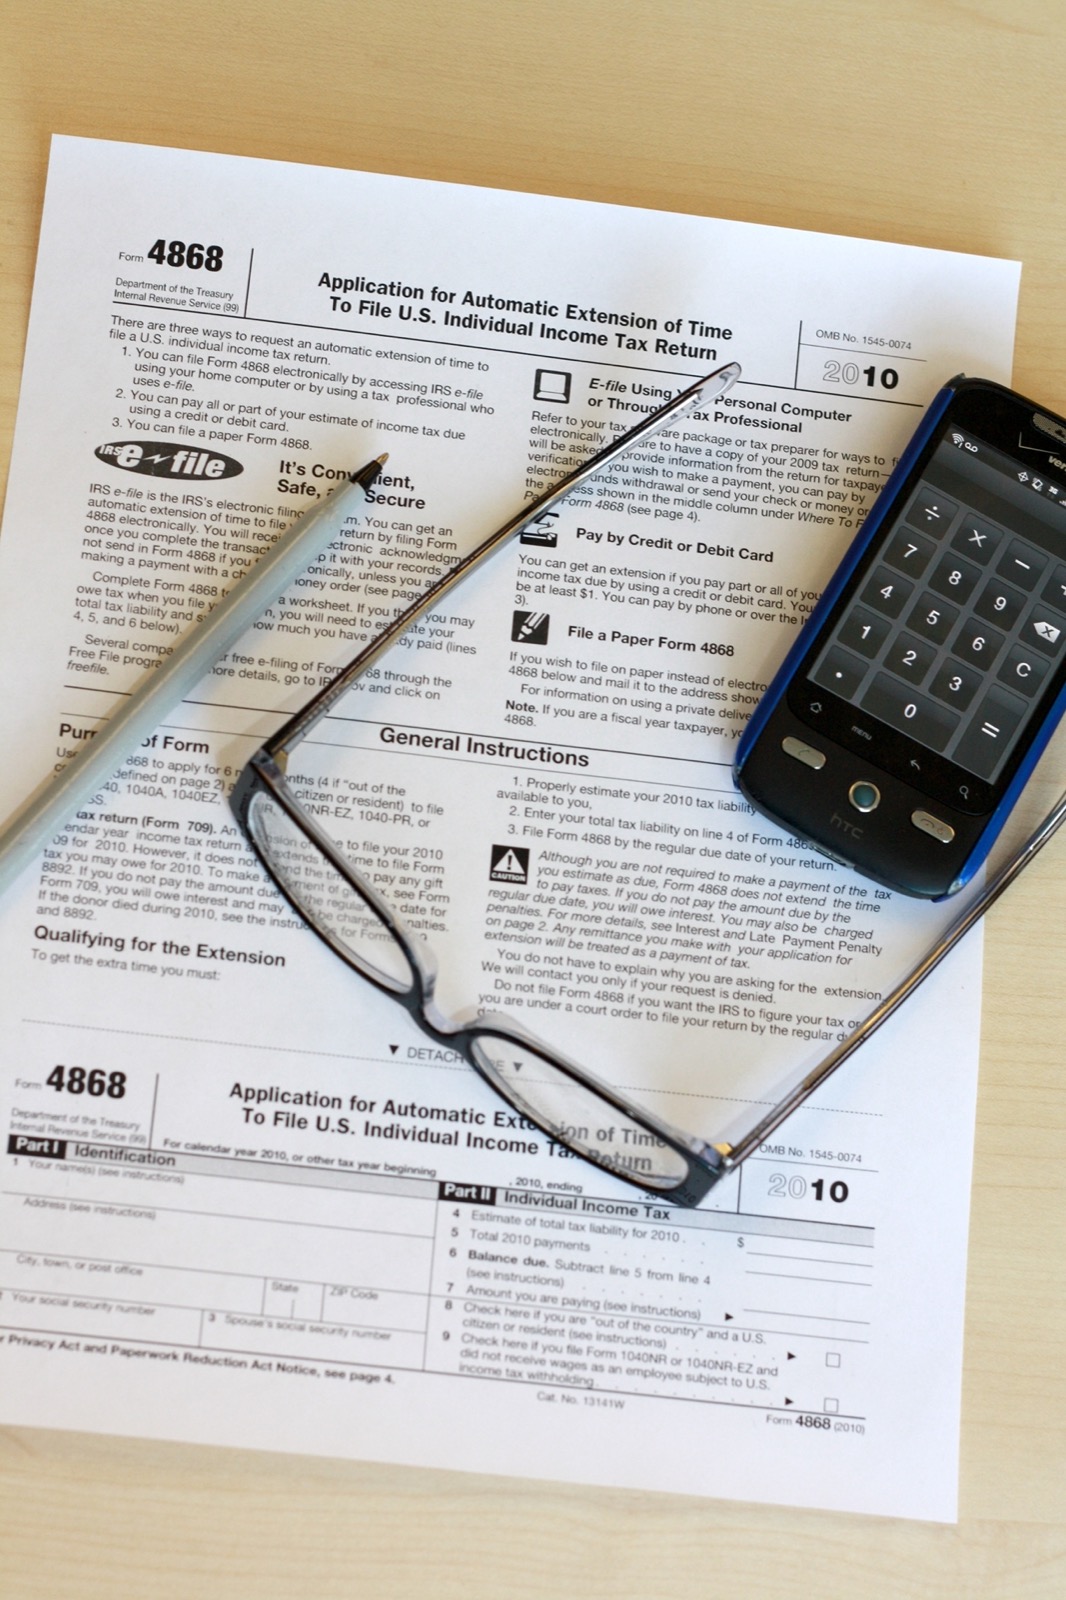
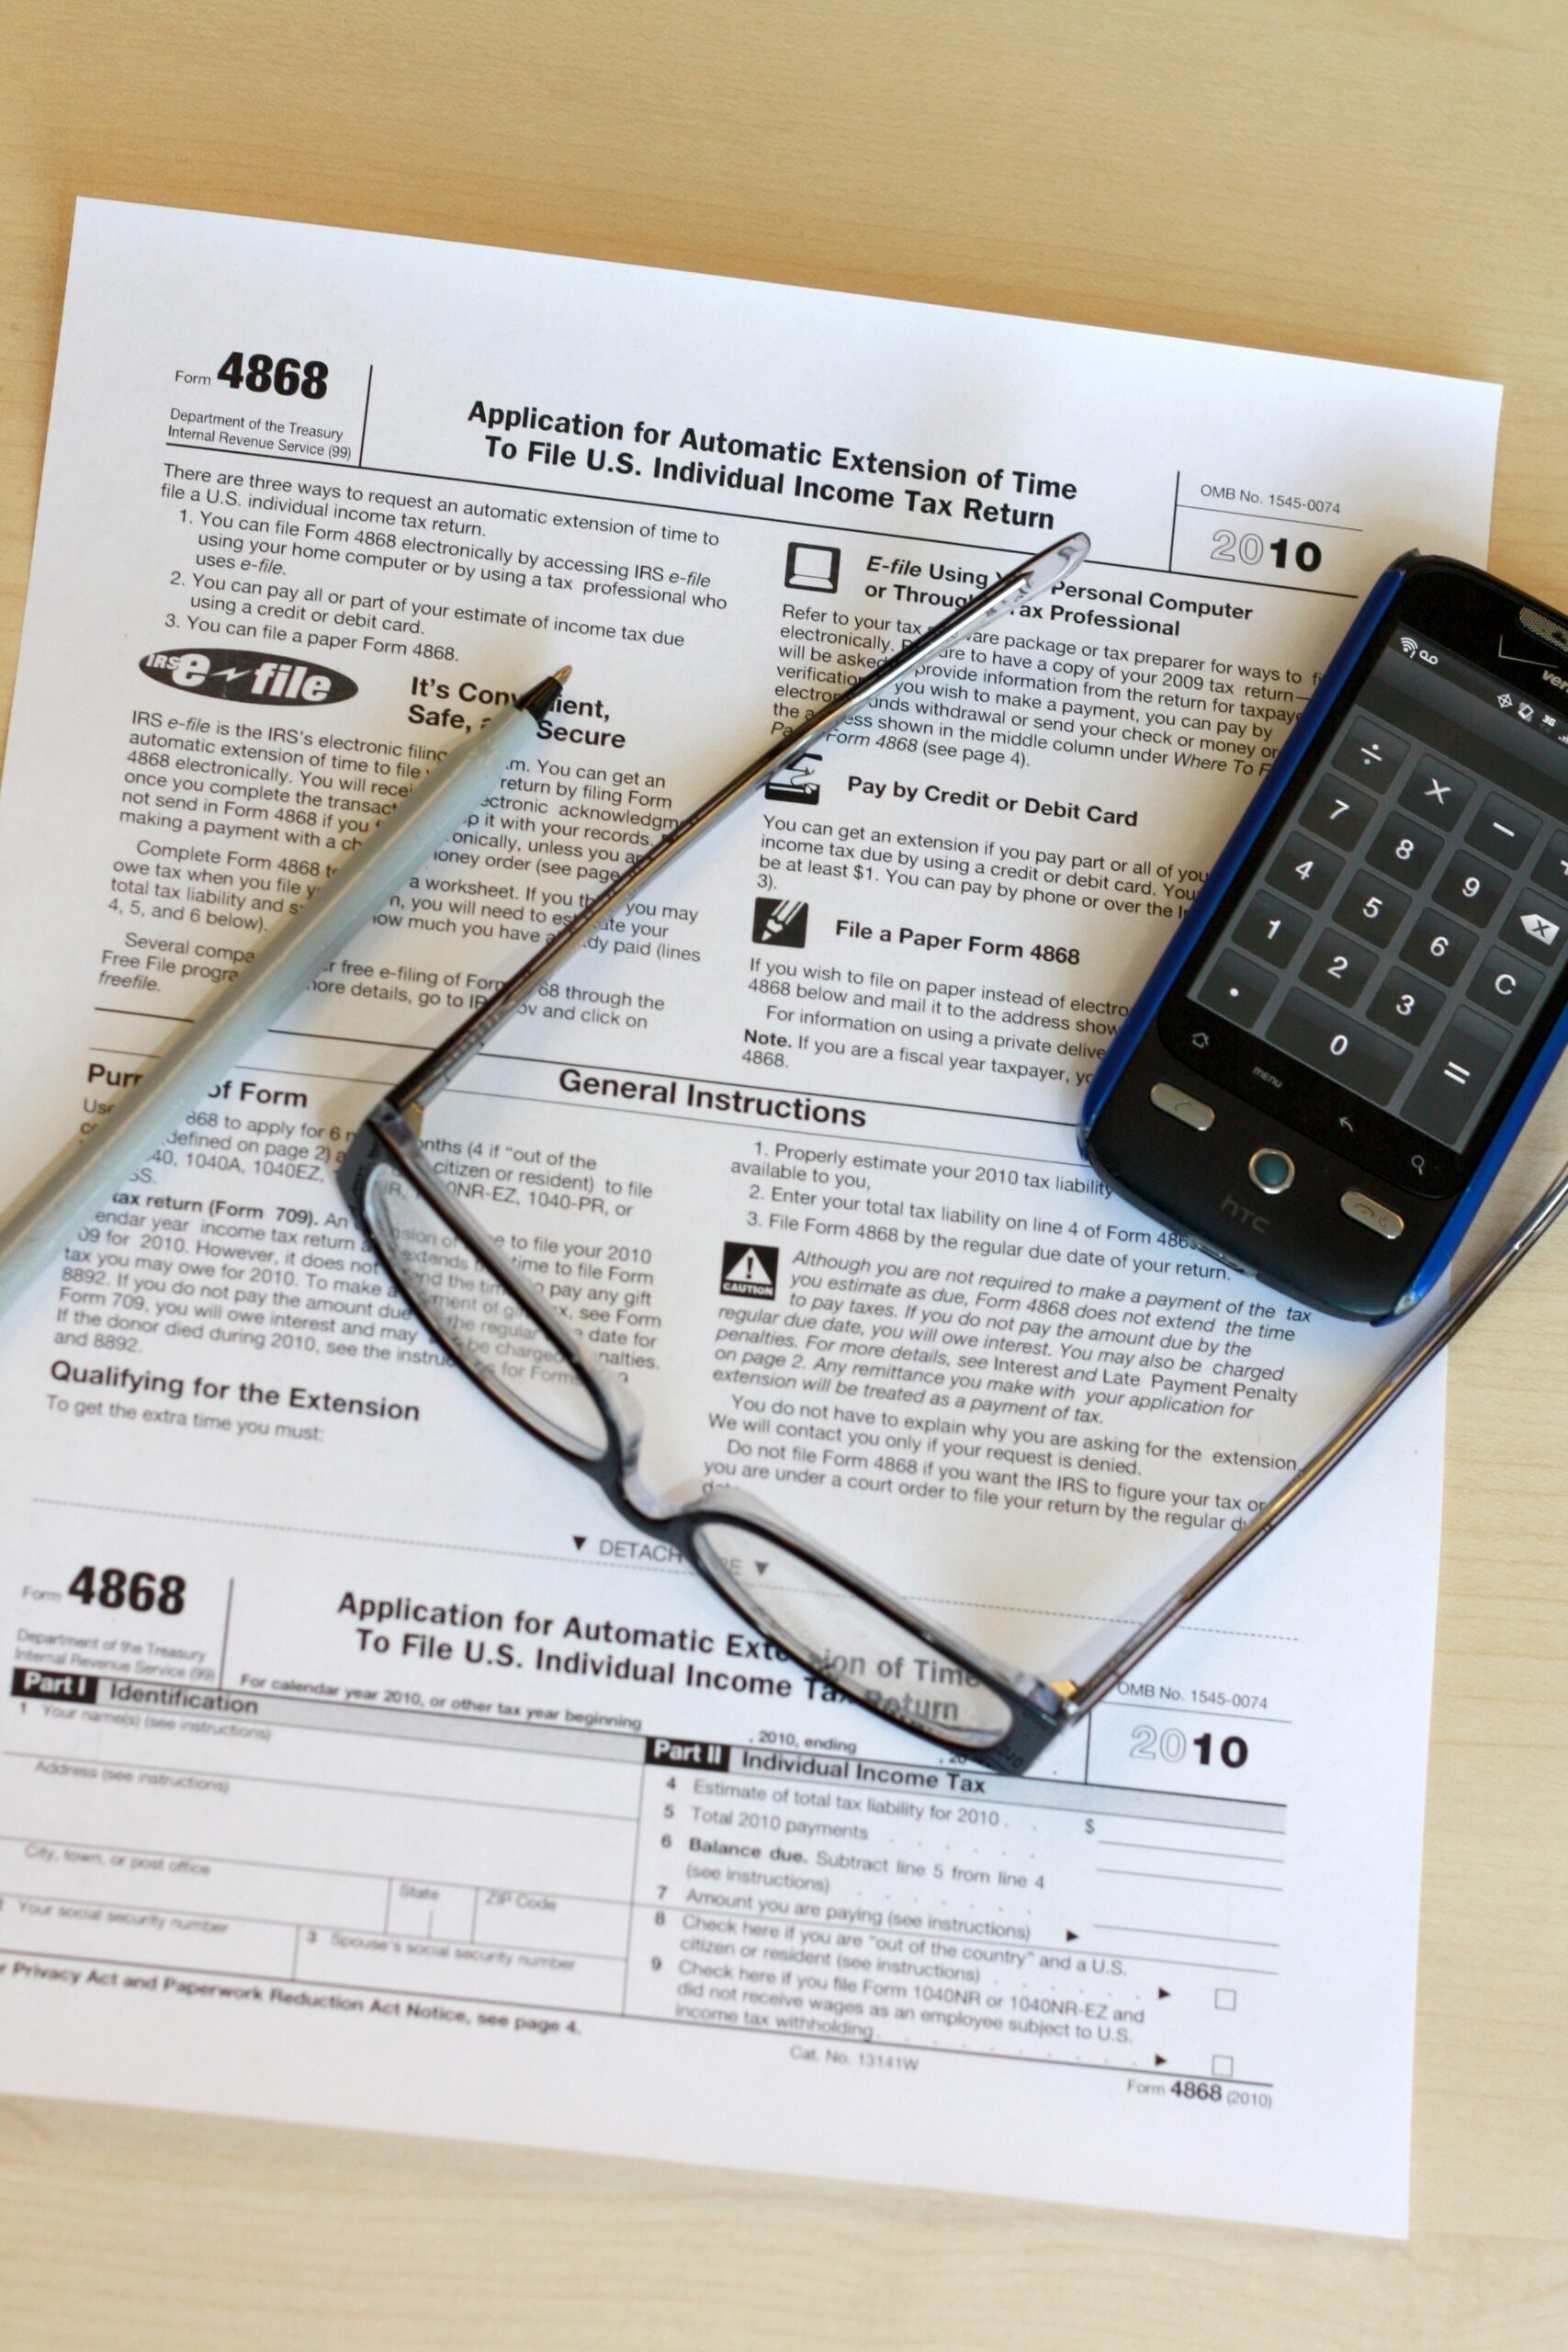
A tax filing extension can give households more time to submit paperwork, but taxes owed still need attention before penalties and interest grow.
A home equity line of credit can be useful, but variable rates, draw periods, repayment shocks, and spending discipline deserve a close look before borrowing.
Health savings accounts can be powerful, but households need qualified-expense records, receipts, and a reimbursement plan that will survive tax time.
Certificates of deposit can offer attractive rates, but early withdrawal penalties, renewal rules, and emergency cash needs deserve a closer look before money is locked away.
A credit freeze can make it harder for identity thieves to open new accounts, but households should understand freezes, fraud alerts, reports, and password cleanup before trouble starts.
Side-gig income can help a household, but taxes, records, estimated payments, and business expenses should be tracked before filing season arrives.
A balance transfer can reduce interest for a while, but transfer fees, promo deadlines, new purchases, and missed payments can weaken the deal.
A higher home insurance deductible can lower premiums, but households should make sure the emergency fund can actually handle a storm, roof, or water-damage claim.
Author’s pick
news via inbox
Subscribe to our newsletter to get latest news & updates.