
Sequence of Returns Risk: Why the First 5 Years of [...]
Hidden Costs of Retiring Abroad: What the Brochures Don’t Tell [...]
The Rule of 55: How to Retire Early Without 10% [...]
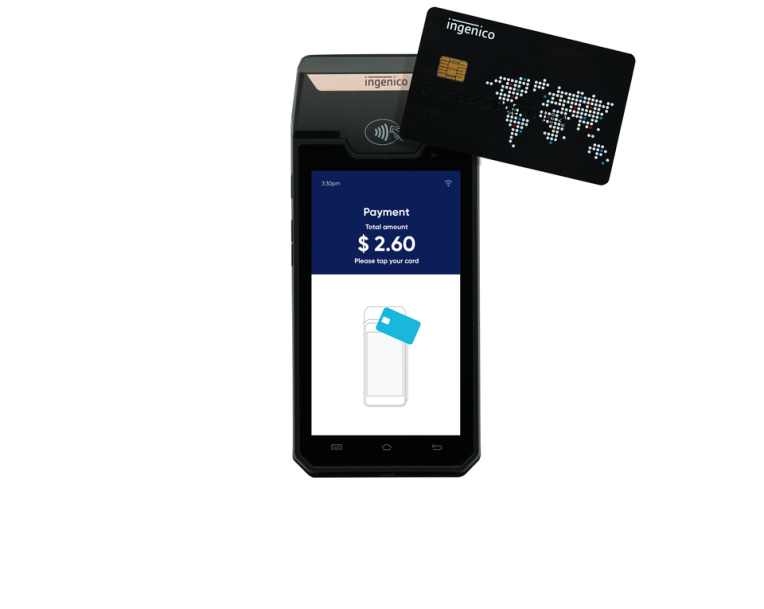
New fintech attention around autonomous AI shopping agents raises a practical consumer question: who is allowed to spend, approve, return, dispute, and explain purchases?
Fresh attention on checking and savings balances by age is useful, but households should read those numbers beside income stability, bills, debt, and access to cash.
Longer auto loans can lower the monthly payment, but households should watch total interest, depreciation, repair risk, and the chance of owing more than the car is worth.
Disputing a credit report error can help, but households should gather statements, notices, identity records, and a clear timeline before sending a vague complaint.
A higher savings rate is useful, but the emergency fund should first be organized around real jobs: deductibles, income gaps, repairs, medical bills, and household surprises.
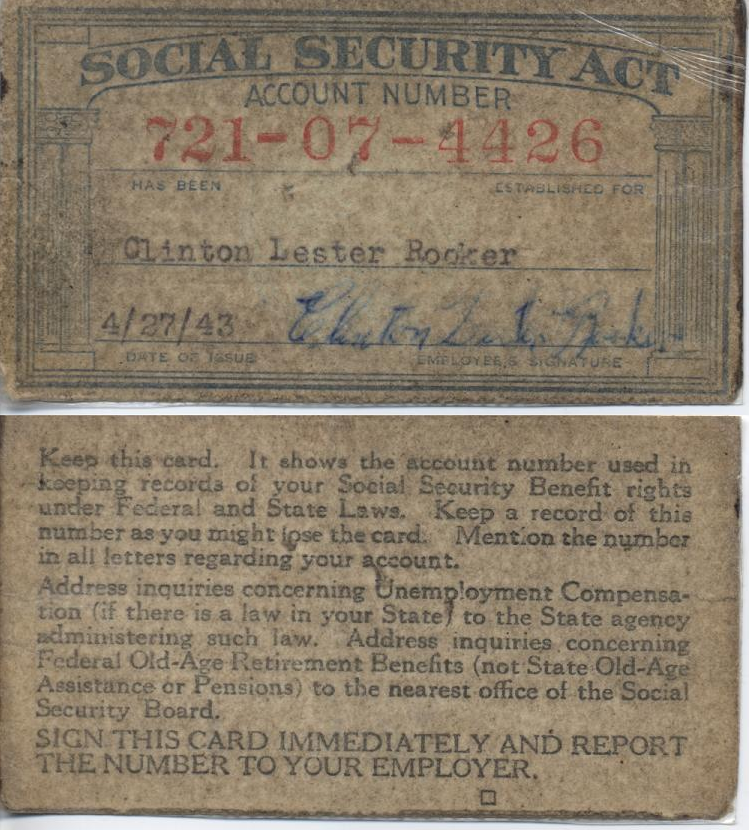
Working while claiming Social Security before full retirement age can reduce benefits temporarily, so households should understand the earnings test before counting every dollar.
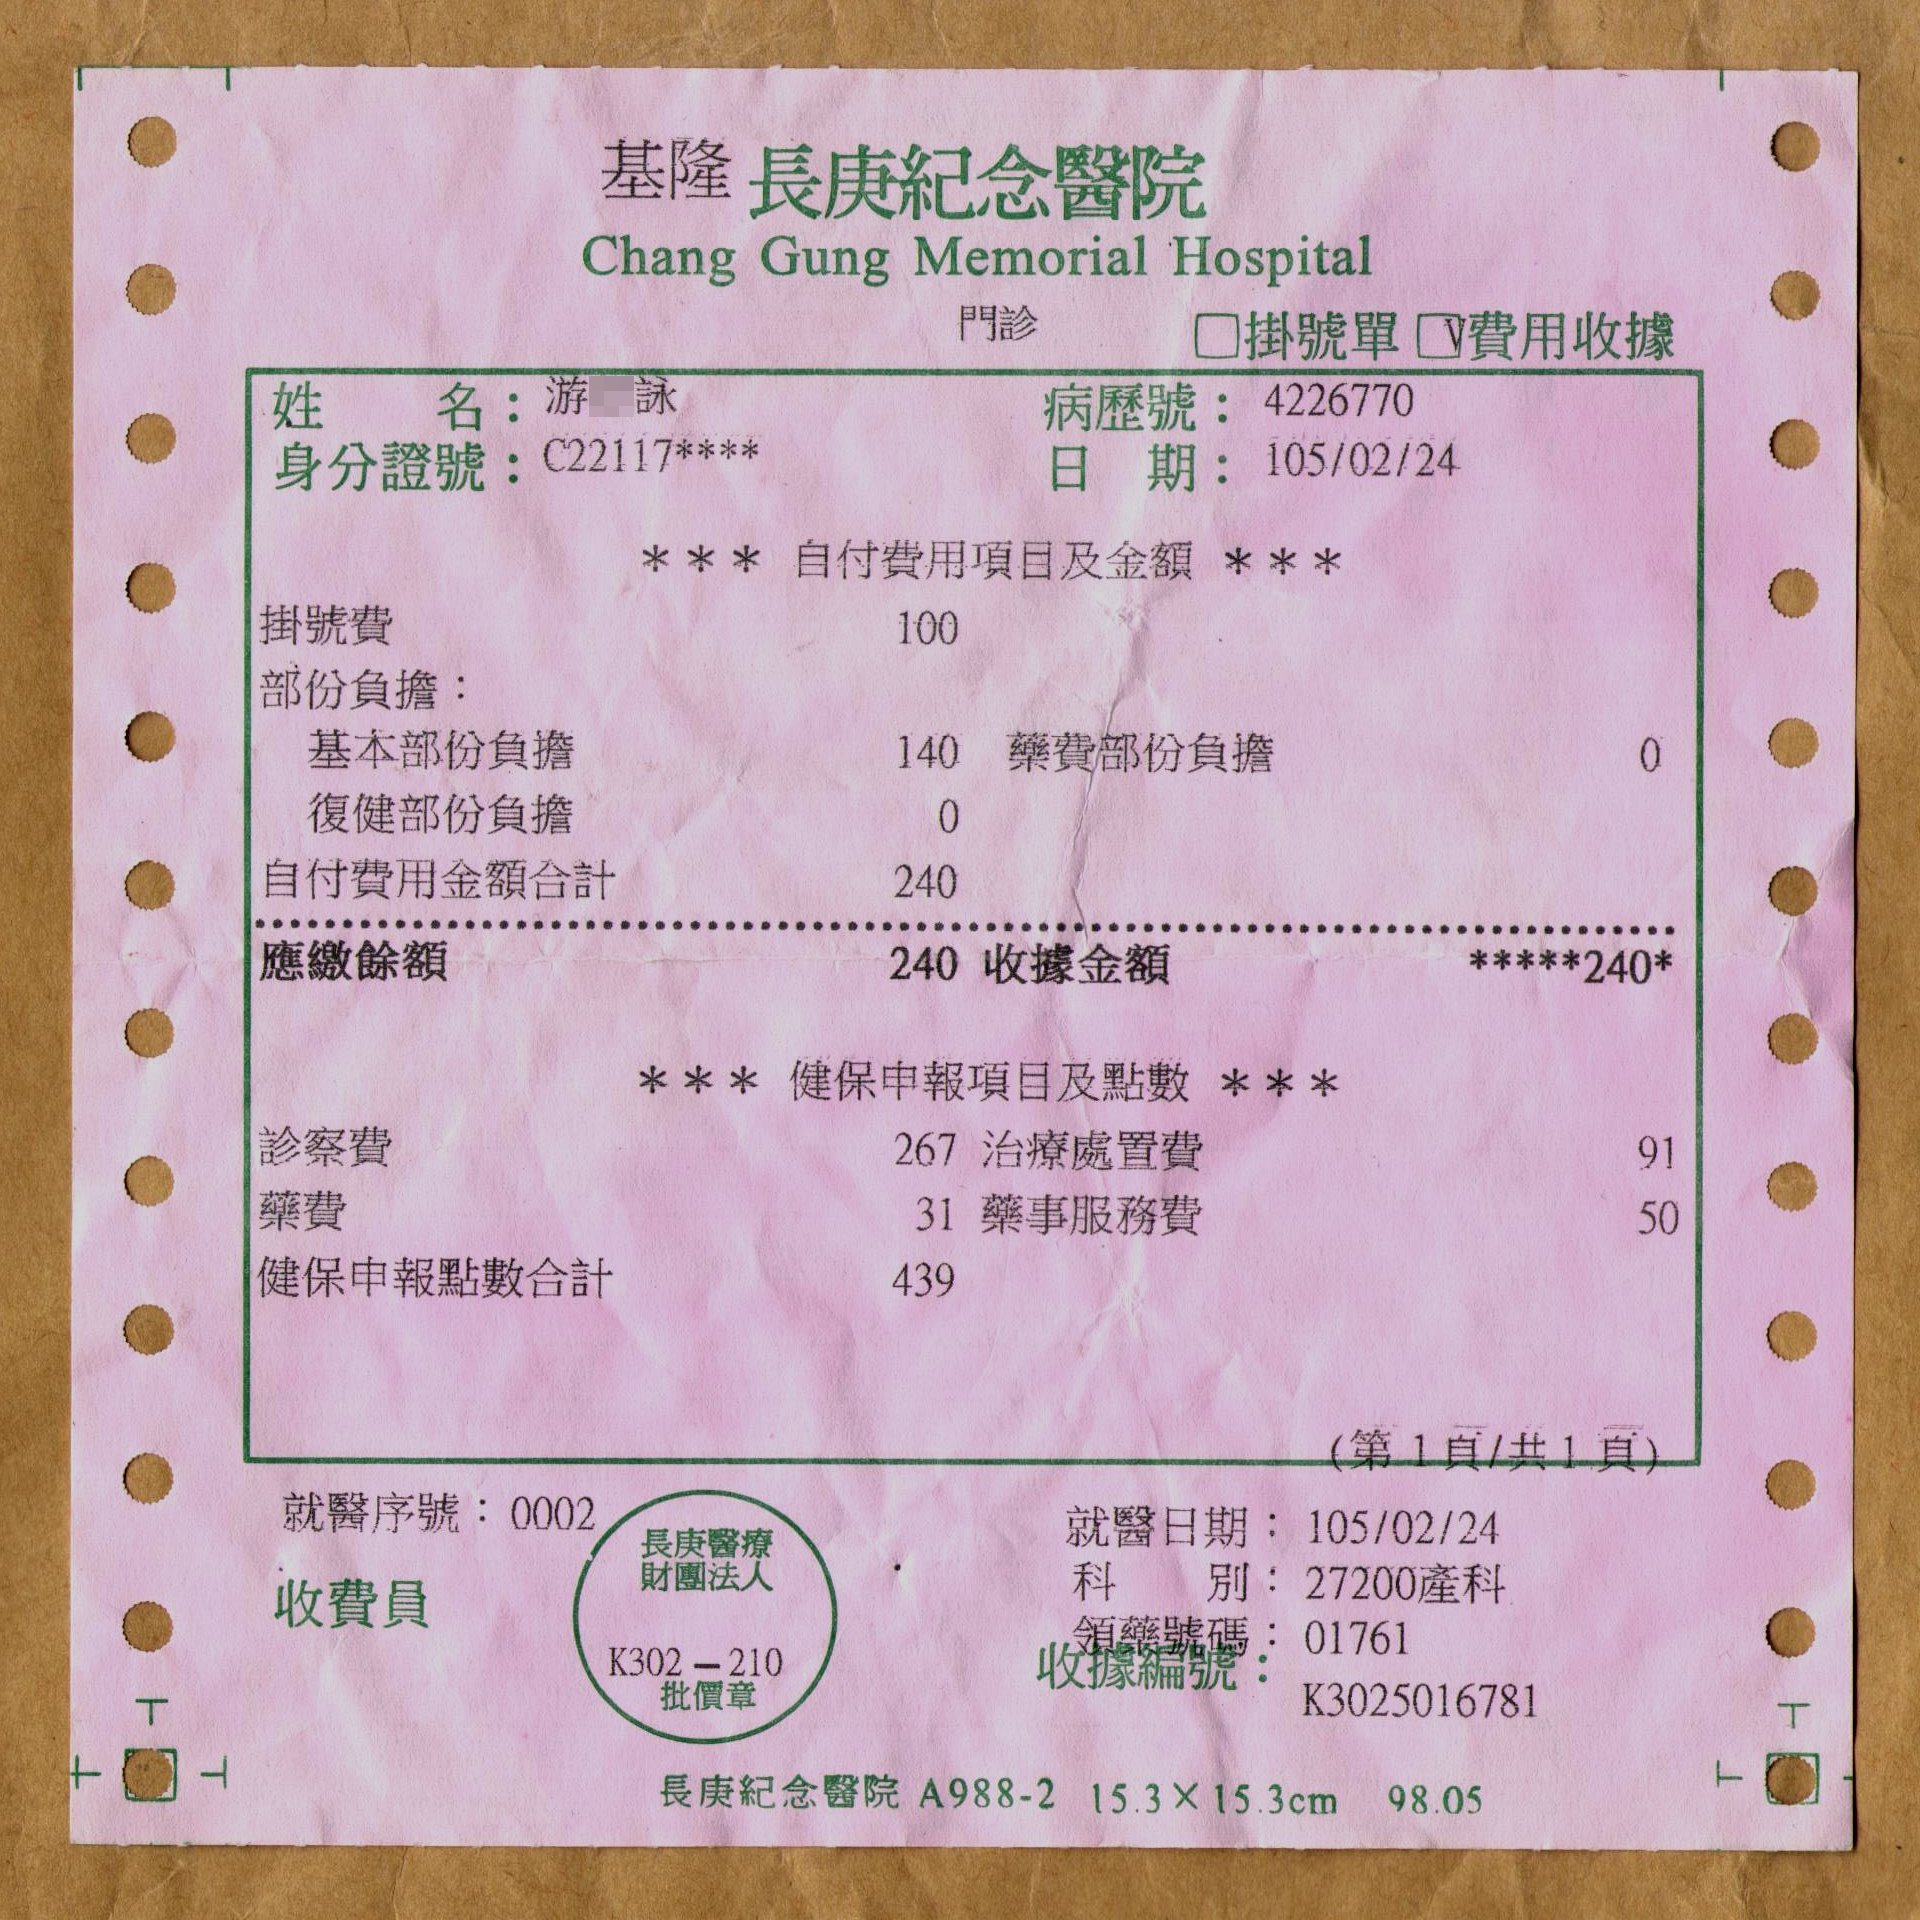
Medical bills can be confusing and urgent-looking, but households should compare insurance notices, ask for itemized bills, and check assistance options before draining savings.
Author’s pick
news via inbox
Subscribe to our newsletter to get latest news & updates.